Go connect is an Australian based company specialising in internet services. They were at a low of .008 in August and have now risen to .024 today. Their announcement on launching their ezybonds platform for retail customers looks promising.
Check out the information on www.asx.com.au GCN code .
Do your own homework and decide for yourself. We could be wrong!
Remember we are not financial advisors.. Sampson management Services (SMS) educate and inform only...We are Assett Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach. Ref standards: AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
Megamoneybox address is http://Megamoneybox.blogspot.com.au We try to help you earn money on the internet.We give free share trading tips. We aim to educate and enthuse. We are in Australia in the land of the Sun. We are asset management and risk consultants, are not financial advisors. You Trade at your own risk. We could be wrong. So do your homework. Go to our other blogs to de stress. We are not big risk takers. We asses, investigate, analyse and then decide.
Showing posts with label australian cheap shares. Show all posts
Showing posts with label australian cheap shares. Show all posts
Thursday, September 8, 2011


Wednesday, September 7, 2011
SO much volatility YET there are opportunities
asx:AIV
ACTIVEX LTD has showed steady gains in the past week. still a bargain at 0.045 and there announcement this week. Gold find at intersection.
Make up your own mind and do your research.
SMA smartrans is another worth watching.
Dont forget NWT..Newstat. at 0.01 has won several contracts and seems on the up.
go to www.asx.com.au and type in the code to view company information. also go to google finance and look at their company info. Google.com/finance gives more financial information as well as a list of comparable companies.
Mega
Remember we are not financial advisors.. Sampson management Services (SMS) educate and inform only...We are Assett Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach. Ref standards: AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
ACTIVEX LTD has showed steady gains in the past week. still a bargain at 0.045 and there announcement this week. Gold find at intersection.
Make up your own mind and do your research.
SMA smartrans is another worth watching.
Dont forget NWT..Newstat. at 0.01 has won several contracts and seems on the up.
go to www.asx.com.au and type in the code to view company information. also go to google finance and look at their company info. Google.com/finance gives more financial information as well as a list of comparable companies.
Mega
Remember we are not financial advisors.. Sampson management Services (SMS) educate and inform only...We are Assett Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach. Ref standards: AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
Friday, July 8, 2011
BDI Blinda at .012 up today by 20%
ASX:BDI Blinda at .012 up today by 20%.
can't see announcement. Put on a watch list.
Remember we are not financial advisors.. Sampson management Services (SMS) educate and inform only...We are Assett Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach. Ref standards: AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
can't see announcement. Put on a watch list.
Remember we are not financial advisors.. Sampson management Services (SMS) educate and inform only...We are Assett Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach. Ref standards: AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
Tuesday, July 5, 2011
TVN Corporation asx:TVN up from .017 to .030 in one week!
TVN Corporation asx:TVN up from .017 to .030 in one week!
bgt 30,000 on 28.6.11 profit so far 380.00 on a small 500.00 + 30 fees.
Worth a small investment..
Remember we are not financial advisors.. Sampson management Services (SMS) educate and inform only...We are Assett Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach. Ref standards: AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
bgt 30,000 on 28.6.11 profit so far 380.00 on a small 500.00 + 30 fees.
Worth a small investment..
Remember we are not financial advisors.. Sampson management Services (SMS) educate and inform only...We are Assett Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach. Ref standards: AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
Tuesday, June 21, 2011
CGT Castelmaine is up 10% already price .044
CGT:ASX Castlemaine is a gold producer I identified in May 2010 price 0.048. At that time the article said that they had purchased the company for a tiny 4.1 million dollars.
I purchased some in ........ and this week they had a big announcement about a major gold find i, possibly the biggest find ever in Victoria, Australia, Ballarat.Ballarat was one of the early goldfields and has produced a huge amount of gold over the years.
Last night there was a 10 min segment on CGT on ABCTV 7.30 report.
So what value would you put on that amount of free advertising!
I think their target market, conservative small cap share traders will jump on board today. Price at close yesterday was only a 0.004 cents. less than half a cent each.
Already today it has risen 10%.
It was a bit of a rush to get some.
CGT expect to reach the rich gold seam by august.
Mega
Remember we are not financial advisors.. Sampson management Services (SMS) educate and inform only...We are Assett Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach. Ref standards: AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
I purchased some in ........ and this week they had a big announcement about a major gold find i, possibly the biggest find ever in Victoria, Australia, Ballarat.Ballarat was one of the early goldfields and has produced a huge amount of gold over the years.
Last night there was a 10 min segment on CGT on ABCTV 7.30 report.
So what value would you put on that amount of free advertising!
I think their target market, conservative small cap share traders will jump on board today. Price at close yesterday was only a 0.004 cents. less than half a cent each.
Already today it has risen 10%.
It was a bit of a rush to get some.
CGT expect to reach the rich gold seam by august.
Mega
Remember we are not financial advisors.. Sampson management Services (SMS) educate and inform only...We are Assett Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach. Ref standards: AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
Monday, June 20, 2011
Re the market is in turmoil BUT theres potential with FML
Just while we feel like being bearish and hiding in a hole on a very bad day, FML Focus minerals rose and there seems to be some good buying.
WHY? because of this announcement below. They are making an offer for Cresent Gold.
Another possible opportunity is CRJ Castemaine. rose today by 12.82 % as per asx.com.au
Code Last % Chg Bid Offer Open High Low Vol
CGT 0.044 12.82% 0.044 0.045 0.043 0.051 0.043 63,970,442
press release
June 20, 2011, 12:06 a.m. EDT
Retransmission: Recommended Takeover of Crescent Gold by Focus Minerals
PERTH, WESTERN AUSTRALIA, Jun 20, 2011 (MARKETWIRE via COMTEX) --
-- Transaction to make Focus one of Australia's Top 5(1) Gold Producers
with a 230,000oz production target in 2012 from multiple open pit and
underground operations
-- Focus offering oneshare for every 1.18 Crescent shares in an off-market
bid
-- Offer represents 30.5% premium to Crescent's last close price of $0.05
per share(2)
-- Crescent Directors unanimously recommend shareholders accept the offer,
in the absence of a Superior Proposal
-- Pre Bid Agreement in favour of Focus for 19.9% of Crescent from Deutsche
Bank group
-- Increased management depth and operational experience to maximise the
value of Crescent's assets
-- Combined group will have a JORC Resource inventory of 4.3Moz of gold(3)
-- Strong rerating potential with the merged proforma EV/Resource multiple
at a 39% discount to the current peer average of A$107/oz
-- Significant synergies in combining two major West Australian mining
regions: Focus' established Coolgardie operations with Crescent's
significant open pit operations at the Laverton Gold Project
-- Combined group will have the financial strength to unlock Crescent's
extensive exploration upside across 1,400km(2) of tenements
Focus Minerals Limited ("Focus") (asx:FML) and Crescent Gold Limited ("Crescent") /quotes/zigman/30819 CA:CRA +10.00% (asx:CRE)(frankfurt:CRE5) are pleased to jointly announce that they have agreed to merge the companies by way of a conditional off-market takeover bid by Focus for all of the issued shares in Crescent ("Offer").
The Crescent Board unanimously recommend the Offer, and intend to accept the Offer in respect of their Crescent holdings, in the absence of a Superior Proposal.
The transaction will make Focus one ofAustralia's Top 5(1) gold producers with targeted annual production of 230,000oz, a combined JORC resource base of 4.3Moz of gold(3), and outstanding growth potential across two major Western Australian mining regions.
OFFER DETAILS
Focus and Crescent have executed a Bid Implementation Agreement ("BIA"), under which Focus agreed to make the Offer. The consideration being offered to Crescent Shareholders is one Focus share for every 1.18 Crescent shares, which represents a premium of 30.5% to Crescent's closing price on 17 June 2011(4).
The Offer is subject to customary conditions, including the following:
-- Minimum acceptance of 90%;
-- No Material Adverse Change; and
-- No prescribed occurrences.
The Offer conditions are set out in Schedule 2 of the BIA in Annexure C. Full particulars of the Offer will be provided in the Bidder's Statement.
The transaction has the support of Crescent's major shareholder, Deutsche Bank AG who has agreed to accept the Offer in respect of a 19.9% stake in Crescent pursuant to a Pre-Bid Agreement with Focus.
At the closing price of Focus shares on 17 June 2011 of 7.7 cents per share, the Offer represents an offer price of 6.5 cents per Crescent share, representing a premium of 30.5% on the closing price of Crescent shares on 17 June 2011 of 5 centsper share, a 29.10% premium to the 5day volume weighted average price ("VWAP") of Crescent shares of 5.1 cents per share and a 20.75% premium to the 30day VWAP of Crescent shares of 5.4 cents per share.
The Offer will be extended to any Crescent shares that are issued during the Offer period as a result of the exercise of Crescent options or conversion of convertible notes on issue before the Offer opens. However, Focus also intends to enter into private treaty arrangements with Crescent option holders to acquire their options in exchange for Focus shares on a ratio determined by reference to the respective exercise price and expiry date of their options.
TRANSACTION HIGHLIGHTS
The Boards of Focus Minerals and Crescent Gold consider that the combination of the two companies will provide significant strategic and financial benefits to both sets of shareholders:
Mr Campbell Baird, Chief Executive Officer of Focus Minerals said: "The merger of Crescent Gold and Focus Minerals provides a unique opportunity for both businesses to fast track their growth aspirations making Focus one of Australia's Top 5 gold producers.
"Once this transaction is complete this creates a strong platform for both companies' shareholders to benefit from a substantial value uplift from a significant increase in combined production, a doubling of gold resources, and the ability to step up exploration within Crescent's extensive landholding," Mr Baird said.
Mr Mark Tory, Managing Director of Crescent Gold said: "The Board of Crescent Gold considers the transaction to be a compelling opportunity for Crescent Shareholders to capture a premium for their shareholding and become part of a major new Australian gold producer. Post-acquisition, Crescent shareholders will be part of an entity with an exciting production and exploration growth profile, strong balance sheet, diversified asset portfolio, and a strong track record in mine operations."
Key compelling benefits for both Focus Minerals and Crescent Gold shareholders include:
-- Creates a Top 5 Australian Gold Producer - With a targeted annual
production of 230,000oz in 2012 and outstanding growth potential across
two major Western Australian mining regions, the combined company will
become a top 5(1)Australian gold producer.
-- Proven Track Record of Mine Operation - Focus has a deep management team
with proven development and mine operation capabilities, having
recommissioned the Three Mile Hill processing plant 18 months ago and
opened two new mining operations in the last three months. Focus will
use this operational expertise to maximise the value of Crescent's
assets.
-- Significant Resource Growth Potential - The combined group will have a
very significant JORC Resource inventory of 4.3Moz(3). Both the Laverton
and Coolgardie regions have demonstrated the opportunity for significant
resource growth on targeted exploration programmes. Focus brings the
immediate funds to accelerate exploration at Laverton, with strong group
revenues providing a basis to fund further exploration to expand group
resources.
-- Strong Operating Cash Flows - The transaction will create a combined
group with very strong anticipated operating cash flow.
-- Valuation Uplift - The implied EV/Resource ratio of the combined entity
is A$66/oz which is a 39% discount to the ASX listed gold producers
average of A$107/oz, implying a significant opportunity for a
revaluation of the combined group.
EXCLUSIVITY ARRANGEMENTS AND PRE-BID WITH CRESCENT SHAREHOLDER
The Board of Directors of Crescent has unanimously recommended that, in the absence of a Superior Proposal all Crescent shareholders accept the Offer, and all directors intend to accept the offer.
Pursuant to the BIA, Focus and Crescent have agreed customary exclusivity arrangements, including "no shop" and "no talk" provisions. The BIA also confers a matching right on Focus. See Annexure C for a copy of the BIA.
Focus has entered into a pre-bid acceptance agreement with Crescent's major shareholder, Deutsche Bank group, which through its wholly owned subsidiary Gulara Pty Ltd owns 29.23% of Crescent. The pre-bid agreement is in respect of 19.9% of Crescent. Separately, Focus has also been informed by Deutsche that its present intention is to accept the Offer in respect of the remaining 9.33%of Crescent shares it holds, no later than five days prior to the end of the Offer period, subject to there being no Superior Proposal. Deutsche Bank has no obligation to accept the Offer in respect of the remaining 9.33% stake and may dispose of these shares to a third party at any time.
LOAN & WORKING CAPITAL FACILITY ARRANGEMENTS
In May 2011 Focus provided a $3 million secured loan to Crescent which upon shareholder approval will turn into a convertible note. Once approved, that convertible note will be convertible into Crescent shares at the conversion price of the lower of $0.05 and 85% of 5 day VWAP of Crescent shares, with 1 free attaching option for each two shares provided.
In addition, on 17 June 2011, Focus provided a $10 million working capital facility to Crescent, which subject to shareholder approval, may be converted into convertible notes. These convertible notes will be convertible to Crescent shares on substantially the same terms as the May 2011 convertible note.
INDICATIVE TIMETABLE
The indicative timetable in relation to the Offer is set out below.
-----------------------------------------------------------------------
-----
Monday, 20 June 2011 Announcement of Transaction
----------------------------------------------------------------------------
Monday, 4 July 2011 Focus lodges its Bidder's Statement with ASIC and ASX
and serves it on Crescent
----------------------------------------------------------------------------
Monday, 4 July 2011 Crescent lodges its Target's Statement with ASIC and
ASX and serves it on Focus
----------------------------------------------------------------------------
Thursday, 7 July 2011 Joint despatch of Bidder's Statement and Target's
Statement
----------------------------------------------------------------------------
Thursday, 7 July 2011 Offer Opens
----------------------------------------------------------------------------
Monday, 8 August 2011 Close of Offer (unless extended)
----------------------------------------------------------------------------
Remember we are not financial advisors.. Sampson management Services (SMS) educate and inform only...We are Assett Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach. Ref standards: AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
WHY? because of this announcement below. They are making an offer for Cresent Gold.
Another possible opportunity is CRJ Castemaine. rose today by 12.82 % as per asx.com.au
Code Last % Chg Bid Offer Open High Low Vol
CGT 0.044 12.82% 0.044 0.045 0.043 0.051 0.043 63,970,442
press release
June 20, 2011, 12:06 a.m. EDT
Retransmission: Recommended Takeover of Crescent Gold by Focus Minerals
PERTH, WESTERN AUSTRALIA, Jun 20, 2011 (MARKETWIRE via COMTEX) --
-- Transaction to make Focus one of Australia's Top 5(1) Gold Producers
with a 230,000oz production target in 2012 from multiple open pit and
underground operations
-- Focus offering oneshare for every 1.18 Crescent shares in an off-market
bid
-- Offer represents 30.5% premium to Crescent's last close price of $0.05
per share(2)
-- Crescent Directors unanimously recommend shareholders accept the offer,
in the absence of a Superior Proposal
-- Pre Bid Agreement in favour of Focus for 19.9% of Crescent from Deutsche
Bank group
-- Increased management depth and operational experience to maximise the
value of Crescent's assets
-- Combined group will have a JORC Resource inventory of 4.3Moz of gold(3)
-- Strong rerating potential with the merged proforma EV/Resource multiple
at a 39% discount to the current peer average of A$107/oz
-- Significant synergies in combining two major West Australian mining
regions: Focus' established Coolgardie operations with Crescent's
significant open pit operations at the Laverton Gold Project
-- Combined group will have the financial strength to unlock Crescent's
extensive exploration upside across 1,400km(2) of tenements
Focus Minerals Limited ("Focus") (asx:FML) and Crescent Gold Limited ("Crescent") /quotes/zigman/30819 CA:CRA +10.00% (asx:CRE)(frankfurt:CRE5) are pleased to jointly announce that they have agreed to merge the companies by way of a conditional off-market takeover bid by Focus for all of the issued shares in Crescent ("Offer").
The Crescent Board unanimously recommend the Offer, and intend to accept the Offer in respect of their Crescent holdings, in the absence of a Superior Proposal.
The transaction will make Focus one ofAustralia's Top 5(1) gold producers with targeted annual production of 230,000oz, a combined JORC resource base of 4.3Moz of gold(3), and outstanding growth potential across two major Western Australian mining regions.
OFFER DETAILS
Focus and Crescent have executed a Bid Implementation Agreement ("BIA"), under which Focus agreed to make the Offer. The consideration being offered to Crescent Shareholders is one Focus share for every 1.18 Crescent shares, which represents a premium of 30.5% to Crescent's closing price on 17 June 2011(4).
The Offer is subject to customary conditions, including the following:
-- Minimum acceptance of 90%;
-- No Material Adverse Change; and
-- No prescribed occurrences.
The Offer conditions are set out in Schedule 2 of the BIA in Annexure C. Full particulars of the Offer will be provided in the Bidder's Statement.
The transaction has the support of Crescent's major shareholder, Deutsche Bank AG who has agreed to accept the Offer in respect of a 19.9% stake in Crescent pursuant to a Pre-Bid Agreement with Focus.
At the closing price of Focus shares on 17 June 2011 of 7.7 cents per share, the Offer represents an offer price of 6.5 cents per Crescent share, representing a premium of 30.5% on the closing price of Crescent shares on 17 June 2011 of 5 centsper share, a 29.10% premium to the 5day volume weighted average price ("VWAP") of Crescent shares of 5.1 cents per share and a 20.75% premium to the 30day VWAP of Crescent shares of 5.4 cents per share.
The Offer will be extended to any Crescent shares that are issued during the Offer period as a result of the exercise of Crescent options or conversion of convertible notes on issue before the Offer opens. However, Focus also intends to enter into private treaty arrangements with Crescent option holders to acquire their options in exchange for Focus shares on a ratio determined by reference to the respective exercise price and expiry date of their options.
TRANSACTION HIGHLIGHTS
The Boards of Focus Minerals and Crescent Gold consider that the combination of the two companies will provide significant strategic and financial benefits to both sets of shareholders:
Mr Campbell Baird, Chief Executive Officer of Focus Minerals said: "The merger of Crescent Gold and Focus Minerals provides a unique opportunity for both businesses to fast track their growth aspirations making Focus one of Australia's Top 5 gold producers.
"Once this transaction is complete this creates a strong platform for both companies' shareholders to benefit from a substantial value uplift from a significant increase in combined production, a doubling of gold resources, and the ability to step up exploration within Crescent's extensive landholding," Mr Baird said.
Mr Mark Tory, Managing Director of Crescent Gold said: "The Board of Crescent Gold considers the transaction to be a compelling opportunity for Crescent Shareholders to capture a premium for their shareholding and become part of a major new Australian gold producer. Post-acquisition, Crescent shareholders will be part of an entity with an exciting production and exploration growth profile, strong balance sheet, diversified asset portfolio, and a strong track record in mine operations."
Key compelling benefits for both Focus Minerals and Crescent Gold shareholders include:
-- Creates a Top 5 Australian Gold Producer - With a targeted annual
production of 230,000oz in 2012 and outstanding growth potential across
two major Western Australian mining regions, the combined company will
become a top 5(1)Australian gold producer.
-- Proven Track Record of Mine Operation - Focus has a deep management team
with proven development and mine operation capabilities, having
recommissioned the Three Mile Hill processing plant 18 months ago and
opened two new mining operations in the last three months. Focus will
use this operational expertise to maximise the value of Crescent's
assets.
-- Significant Resource Growth Potential - The combined group will have a
very significant JORC Resource inventory of 4.3Moz(3). Both the Laverton
and Coolgardie regions have demonstrated the opportunity for significant
resource growth on targeted exploration programmes. Focus brings the
immediate funds to accelerate exploration at Laverton, with strong group
revenues providing a basis to fund further exploration to expand group
resources.
-- Strong Operating Cash Flows - The transaction will create a combined
group with very strong anticipated operating cash flow.
-- Valuation Uplift - The implied EV/Resource ratio of the combined entity
is A$66/oz which is a 39% discount to the ASX listed gold producers
average of A$107/oz, implying a significant opportunity for a
revaluation of the combined group.
EXCLUSIVITY ARRANGEMENTS AND PRE-BID WITH CRESCENT SHAREHOLDER
The Board of Directors of Crescent has unanimously recommended that, in the absence of a Superior Proposal all Crescent shareholders accept the Offer, and all directors intend to accept the offer.
Pursuant to the BIA, Focus and Crescent have agreed customary exclusivity arrangements, including "no shop" and "no talk" provisions. The BIA also confers a matching right on Focus. See Annexure C for a copy of the BIA.
Focus has entered into a pre-bid acceptance agreement with Crescent's major shareholder, Deutsche Bank group, which through its wholly owned subsidiary Gulara Pty Ltd owns 29.23% of Crescent. The pre-bid agreement is in respect of 19.9% of Crescent. Separately, Focus has also been informed by Deutsche that its present intention is to accept the Offer in respect of the remaining 9.33%of Crescent shares it holds, no later than five days prior to the end of the Offer period, subject to there being no Superior Proposal. Deutsche Bank has no obligation to accept the Offer in respect of the remaining 9.33% stake and may dispose of these shares to a third party at any time.
LOAN & WORKING CAPITAL FACILITY ARRANGEMENTS
In May 2011 Focus provided a $3 million secured loan to Crescent which upon shareholder approval will turn into a convertible note. Once approved, that convertible note will be convertible into Crescent shares at the conversion price of the lower of $0.05 and 85% of 5 day VWAP of Crescent shares, with 1 free attaching option for each two shares provided.
In addition, on 17 June 2011, Focus provided a $10 million working capital facility to Crescent, which subject to shareholder approval, may be converted into convertible notes. These convertible notes will be convertible to Crescent shares on substantially the same terms as the May 2011 convertible note.
INDICATIVE TIMETABLE
The indicative timetable in relation to the Offer is set out below.
-----------------------------------------------------------------------
-----
Monday, 20 June 2011 Announcement of Transaction
----------------------------------------------------------------------------
Monday, 4 July 2011 Focus lodges its Bidder's Statement with ASIC and ASX
and serves it on Crescent
----------------------------------------------------------------------------
Monday, 4 July 2011 Crescent lodges its Target's Statement with ASIC and
ASX and serves it on Focus
----------------------------------------------------------------------------
Thursday, 7 July 2011 Joint despatch of Bidder's Statement and Target's
Statement
----------------------------------------------------------------------------
Thursday, 7 July 2011 Offer Opens
----------------------------------------------------------------------------
Monday, 8 August 2011 Close of Offer (unless extended)
----------------------------------------------------------------------------
Remember we are not financial advisors.. Sampson management Services (SMS) educate and inform only...We are Assett Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach. Ref standards: AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
Wednesday, May 25, 2011
post from www.asxguru.com.au
here's something interesting
May 22, 2011Comments Off
Carbon Tax Will Cost JobsCategories: Sundry
Back in April I posted about an article that alluded to the possibility of the carbon tax actually leading to the increase of pollution as heavy carbon emitting industries pack up and move offshore. Not only that – a significant number of Australian jobs will be lost as well!
Those who support the carbon tax have preached about the new economy and how the tax will lead to job creation and new opportunities. This sort of talk is just that – talk! The reality will most likely be that entire sectors of industry will fold up their operations and move offshore. With that will go thousands of jobs.
At the beginning of this week, supporters of a carbon emissions tax were heralding the news of a substantial increase in carbon reduction targets from Britain. But then just a few days later, the consequences of that decision became clear with one of the world’s largest steel produces Tata Steel deciding to cut 1,500 in Britain.
This article from The Australian reports on the development and to quote from it;
Karl-Ulrich Kohler, Tata Steel’s head of Europe, blamed the cuts on the decline of the construction industry, but added that new EU environmental laws and planned British legislation had compounded the company’s problems.
“Europe’s steel industry is in danger of being made uncompetitive in the world market because of European taxes on UK emissions,” said Dr Kohler.
“But here in Britain we are facing a double whammy of carbon targets.”
Under the coalition deal, the government plans to bring in the toughest carbon emissions targets in the world by 2027. The EU has already said that member states must slash emissions, but Britain will go farther and cut them by 80 per cent by 2050.
Godfrey Bloom, the UKIP MEP in whose Yorkshire & North Lincolnshire constituency the Scunthorpe cuts will fall, said the “misguided” carbon legislation had made “a bad commercial situation far, far worse”.
He added: “Certain extra costs and additional targets are clearly undermining business confidence. The result, as we see, is lost jobs.”
We are seeing the very same message from sectors of Australian industry – warning of the dire consequences.
ref www.asxguru.com.au
Remember we are not financial advisors.. Sampson management Services (SMS) educate and inform only...We are Assett Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach. Ref standards: AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
May 22, 2011Comments Off
Carbon Tax Will Cost JobsCategories: Sundry
Back in April I posted about an article that alluded to the possibility of the carbon tax actually leading to the increase of pollution as heavy carbon emitting industries pack up and move offshore. Not only that – a significant number of Australian jobs will be lost as well!
Those who support the carbon tax have preached about the new economy and how the tax will lead to job creation and new opportunities. This sort of talk is just that – talk! The reality will most likely be that entire sectors of industry will fold up their operations and move offshore. With that will go thousands of jobs.
At the beginning of this week, supporters of a carbon emissions tax were heralding the news of a substantial increase in carbon reduction targets from Britain. But then just a few days later, the consequences of that decision became clear with one of the world’s largest steel produces Tata Steel deciding to cut 1,500 in Britain.
This article from The Australian reports on the development and to quote from it;
Karl-Ulrich Kohler, Tata Steel’s head of Europe, blamed the cuts on the decline of the construction industry, but added that new EU environmental laws and planned British legislation had compounded the company’s problems.
“Europe’s steel industry is in danger of being made uncompetitive in the world market because of European taxes on UK emissions,” said Dr Kohler.
“But here in Britain we are facing a double whammy of carbon targets.”
Under the coalition deal, the government plans to bring in the toughest carbon emissions targets in the world by 2027. The EU has already said that member states must slash emissions, but Britain will go farther and cut them by 80 per cent by 2050.
Godfrey Bloom, the UKIP MEP in whose Yorkshire & North Lincolnshire constituency the Scunthorpe cuts will fall, said the “misguided” carbon legislation had made “a bad commercial situation far, far worse”.
He added: “Certain extra costs and additional targets are clearly undermining business confidence. The result, as we see, is lost jobs.”
We are seeing the very same message from sectors of Australian industry – warning of the dire consequences.
ref www.asxguru.com.au
Remember we are not financial advisors.. Sampson management Services (SMS) educate and inform only...We are Assett Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach. Ref standards: AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
Sunday, October 3, 2010
CMY - thorium
ASX:CMY produces Thorium, and has risen from 7 cents to 14 cents.
there has been a few risers lately in my under ten cent shares portfolio.
check it out here
http://finance.yahoo.com/q/ta?s=CMY.AX&t=1y&l=on&z=l&q=l&p=b,p&a=&c=
I'll post more tips lat er...
a $500.00 investment might pay off in the next few months.
Thorium is a much wanted commodity.
ASX:ABY is another. Copper production. I bgt in at 1.00 and its up to 1.14. that's 14%.
If you can't afford gold, copper is best.
I made some money when it was as low as 12 cents. I wish I hadn't sold!
Mega
Remember we are not financial advisors.. Sampson management Services (SMS) educate and inform only...We are Assett Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach. Ref standards: AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
there has been a few risers lately in my under ten cent shares portfolio.
check it out here
http://finance.yahoo.com/q/ta?s=CMY.AX&t=1y&l=on&z=l&q=l&p=b,p&a=&c=
I'll post more tips lat er...
a $500.00 investment might pay off in the next few months.
Thorium is a much wanted commodity.
ASX:ABY is another. Copper production. I bgt in at 1.00 and its up to 1.14. that's 14%.
If you can't afford gold, copper is best.
I made some money when it was as low as 12 cents. I wish I hadn't sold!
Mega
Remember we are not financial advisors.. Sampson management Services (SMS) educate and inform only...We are Assett Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach. Ref standards: AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
Friday, June 11, 2010
http://www.proactiveinvestors.co.uk/companies/news/17568/bhp-billiton-chairman-jac-nasser-slams-australian-mining-super-tax-17568.html
Friday, June 11, 2010 by Jamie Ashcroft
BHP noted its disappointment that such a consultation has not been possible in relation to the ‘super-tax’. “Therefore the government missed the opportunity to have Treasury's theory tested by practical experience and industry knowledge”, Nasser stated.
“We always welcome the opportunity to consult but unfortunately ... there has been no acknowledgement by the government of the major flaws of the proposed tax and the significant impact on the industry”. BHP said it is not against tax reform, but it believes that the principles of sound tax reform are not present in the current proposal.
“The 40 per cent super tax rate, in addition to company tax, will make the Australian mineral resources industry the highest taxed in the world and uncompetitive with other resource-rich nations. An uncompetitive tax rate is a fundamental problem.”
“The super tax will apply to existing projects, fundamentally changing the rules when billions of dollars have already been invested.”
According to BHP, any new tax on the minerals resources industry should: Not fundamentally change the rules of the game on existing projects; Ensure that overall tax is competitive with other mineral resources countries; Vary between the kind of mineral resources mined; Be applied on the value of minerals alone.
Otherwise, the company believes that the proposal could damage Australia's reputation as a stable and fair place for investment, the country could lose investment to countries with more attractive tax rates, and it could unintentionally penalise investments in infrastructure, processing or other support activities.
“The Australian government needs to understand the real world impact of the proposed super tax or it will hurt the Australian minerals industry and hurt Australia's future,” Nasser said.
BHP also told its shareholders that it wanted to set the record straight, in terms of its own tax payments in Australia. “The government has not accurately represented the level of taxes we pay on our Australian operations ... It concerns BHP Billiton that inappropriate conclusions appear to have been drawn ... Total taxes paid by BHP Billiton's Australian operations in relation to the financial years 2004 to 2009 inclusive exceed A$24 billion."
“The 2009 earnings of BHP Billiton's Australian operations were almost fully reinvested back in Australia,” he added
Remember we are not financial advisors.. Sampson management Services (SMS) educate and inform only...We are Asset Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach. Ref standards:AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
Friday, June 11, 2010 by Jamie Ashcroft
BHP noted its disappointment that such a consultation has not been possible in relation to the ‘super-tax’. “Therefore the government missed the opportunity to have Treasury's theory tested by practical experience and industry knowledge”, Nasser stated.
“We always welcome the opportunity to consult but unfortunately ... there has been no acknowledgement by the government of the major flaws of the proposed tax and the significant impact on the industry”. BHP said it is not against tax reform, but it believes that the principles of sound tax reform are not present in the current proposal.
“The 40 per cent super tax rate, in addition to company tax, will make the Australian mineral resources industry the highest taxed in the world and uncompetitive with other resource-rich nations. An uncompetitive tax rate is a fundamental problem.”
“The super tax will apply to existing projects, fundamentally changing the rules when billions of dollars have already been invested.”
According to BHP, any new tax on the minerals resources industry should: Not fundamentally change the rules of the game on existing projects; Ensure that overall tax is competitive with other mineral resources countries; Vary between the kind of mineral resources mined; Be applied on the value of minerals alone.
Otherwise, the company believes that the proposal could damage Australia's reputation as a stable and fair place for investment, the country could lose investment to countries with more attractive tax rates, and it could unintentionally penalise investments in infrastructure, processing or other support activities.
“The Australian government needs to understand the real world impact of the proposed super tax or it will hurt the Australian minerals industry and hurt Australia's future,” Nasser said.
BHP also told its shareholders that it wanted to set the record straight, in terms of its own tax payments in Australia. “The government has not accurately represented the level of taxes we pay on our Australian operations ... It concerns BHP Billiton that inappropriate conclusions appear to have been drawn ... Total taxes paid by BHP Billiton's Australian operations in relation to the financial years 2004 to 2009 inclusive exceed A$24 billion."
“The 2009 earnings of BHP Billiton's Australian operations were almost fully reinvested back in Australia,” he added
Remember we are not financial advisors.. Sampson management Services (SMS) educate and inform only...We are Asset Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach. Ref standards:AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
Monday, June 7, 2010
free tips
free aussie sharemarke tip for today. follow carzyjimsmith on twitter
#asx CAP still going strong! 38c
14 minutes ago via web
Remember we are not financial advisors.. Sampson management Services (SMS) educate and inform only...We are Asset Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach. Ref standards:AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
#asx CAP still going strong! 38c
14 minutes ago via web
Remember we are not financial advisors.. Sampson management Services (SMS) educate and inform only...We are Asset Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach. Ref standards:AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
Friday, May 28, 2010
About the mining resource supertax
Date/Time: 2010:05:27 02:04:58 Source: The Australian
THE Rudd government is moving towards a major backdown on its $12 billion tax on resources, redefining its proposed super-profits levy, but the big mining companies have declared the changes do not stop the risk to investment in Australia.
Only three weeks after unveiling the new resource super-profits tax, the government is preparing to lift the threshold definition of a super profit from 6 per cent to 11 or 12 per cent following a ferocious campaign by the mining companies.
To offset the lost revenue in raising the threshold to the same level as the existing petroleum resources rent tax, which applies to offshore gasfields, the government intends to withdraw the 40 per cent taxpayer-funded compensation originally offered for mining projects that fail.
But all the major mining companies have rejected the new proposals as "tinkering at the edges" and not addressing the main risk to mining investment in Australia. The mining companies are demanding more negotiation with the government on the issues of the retrospective application of the new tax, different rates for different minerals and the 40 per cent tax rate.
Start of sidebar. Skip to end of sidebar.
Related Coverage
DU PLESSIS: Rio boss returns fire at Swan
OFFICIAL: Outcry only scaring investors
RICH LIST: Mining magnates dig in
DENNIS SHANAHAN: Judges give Rudd a big zero
DESPATCH BOX: And then Papa Bear said...
VIDEO: Resources tax minefield
IN DEPTH: Henry Tax Review
Mining tax won't raise prices - Henry Daily Telegraph, 11 hours ago
$27bn ore exports at risk The Australian, 20 hours ago
Treasury boss defends mine tax Herald Sun, 1 day ago
Good policy the winner as Labor rethinks its tax The Australian, 1 day ago
Miners paid extra in boom time Perth Now, 2 days ago
End of sidebar. Return to start of sidebar.
BHP Billiton chief executive Marius Kloppers declared last night that any thought the petroleum tax would work for minerals was "naive" and demonstrated "a lack of knowledge as to how investments are made".
"Most importantly, we must understand that for each mineral we are competing against other investment destinations, and each set of minerals has a different set of competitors and those competitors set the price," Mr Kloppers told The Australian.
And Xstrata chief executive Mick Davis said from South Africa: "The government needs to do what it should have done all along and enter into full and open consultations with the industry where every aspect of the super tax is open for debate. Tinkering at the margins will not avoid the significant long-term damage this tax could do to mining investment in Australia.
"The government should stop negotiating with itself and start consulting with the industry."
Rio Tinto chairman Jan du Plessis told the company's shareholders that Australia's reputation had already been damaged by the super-profits tax proposal.
"We are concerned that the proposed resources super tax will erode Australia's competitiveness, severely curtail investment and limit jobs growth," Mr du Plessis said yesterday. He said that some of the government's arguments for the tax and some of the statistics that had been produced to support them "could only be described as scandalous, totally scandalous".
Wayne Swan continued his criticisms of the mining companies yesterday, telling parliament they were still paying only 17c in the dollar in tax compared with the "headline rate" of 30 per cent. The Treasurer vowed to keep the 40 per cent rate for the new RSPT.
"What we have to do is extract the maximum value for the Australian people as we go forward to reform our economy, to invest in our economy and to ensure our prosperity as we go forward," Mr Swan said.
Earlier, he said the government was "interested and fair dinkum about consultation".
"The government is involved in consultation," Mr Swan said. "First of all, we have our consultation panel. Over 80 companies have been through that panel process and are talking to that panel. In addition to that, the government is continuing to talk to many mining companies about their views.
"What we are going to get for the Australian people is a fair share of the resources they own 100 per cent, a fair share - a tax which encourages investment and growth in the industry."
The government's consultation panel, headed by Treasury deputy secretary David Parker, will give its first report to the government tomorrow. It is expected to go beyond its strict limits for discussion and recommend the raising of the threshold for the super-profits tax to be lifted from 6 per cent, the long-term government bond rate, to about 11 or 12 per cent, the bond rate plus five or six percentage points.
As reported in The Australian on Monday, the lost revenue would be covered by the withdrawal of the 40 per cent compensation for failed projects to enable the government to keep its budget projections, including a $1bn surplus in 2012-13, intact.
Mr Parker said yesterday the proposed RSPT as a result of the Henry tax review was "the architecture of reform, not the engineering drawings".
"With such reforms, there will always be winners and losers, with some groups more vocal than others," Mr Parker said. "The challenge is to work together to address the issues that will inevitably arise."
Government sources confirmed that the panel was expected to recommend major changes to the proposed RSPT, including raising the threshold, but others warned it was unlikely there would be an early settlement of the negotiations with the mining companies.
In Adelaide, Mr Kloppers said a 40 per cent tax rate may have been considered appropriate when it was devised for the petroleum industry in the 1980s after two years of consultation but it was "a giant, naive extrapolation to think miraculously the same one is the appropriate rate for every mineral in 2010".
"BHP Billiton, being in the oil and gas industry and in the minerals industry, has experience on both sides and, more than other players, we understand the difference between the products themselves and between minerals more broadly," he said.
"Retrospectivity on this tax is the key determinant for Australia as a destination for investment.
"It goes against the core offering that Australia has, which is being a stable place for investment."
67 comments on this story
Remember we are not financial advisors.. Sampson management Services (SMS) educate and inform only...We are Asset Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach. Ref standards:AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
THE Rudd government is moving towards a major backdown on its $12 billion tax on resources, redefining its proposed super-profits levy, but the big mining companies have declared the changes do not stop the risk to investment in Australia.
Only three weeks after unveiling the new resource super-profits tax, the government is preparing to lift the threshold definition of a super profit from 6 per cent to 11 or 12 per cent following a ferocious campaign by the mining companies.
To offset the lost revenue in raising the threshold to the same level as the existing petroleum resources rent tax, which applies to offshore gasfields, the government intends to withdraw the 40 per cent taxpayer-funded compensation originally offered for mining projects that fail.
But all the major mining companies have rejected the new proposals as "tinkering at the edges" and not addressing the main risk to mining investment in Australia. The mining companies are demanding more negotiation with the government on the issues of the retrospective application of the new tax, different rates for different minerals and the 40 per cent tax rate.
Start of sidebar. Skip to end of sidebar.
Related Coverage
DU PLESSIS: Rio boss returns fire at Swan
OFFICIAL: Outcry only scaring investors
RICH LIST: Mining magnates dig in
DENNIS SHANAHAN: Judges give Rudd a big zero
DESPATCH BOX: And then Papa Bear said...
VIDEO: Resources tax minefield
IN DEPTH: Henry Tax Review
Mining tax won't raise prices - Henry Daily Telegraph, 11 hours ago
$27bn ore exports at risk The Australian, 20 hours ago
Treasury boss defends mine tax Herald Sun, 1 day ago
Good policy the winner as Labor rethinks its tax The Australian, 1 day ago
Miners paid extra in boom time Perth Now, 2 days ago
End of sidebar. Return to start of sidebar.
BHP Billiton chief executive Marius Kloppers declared last night that any thought the petroleum tax would work for minerals was "naive" and demonstrated "a lack of knowledge as to how investments are made".
"Most importantly, we must understand that for each mineral we are competing against other investment destinations, and each set of minerals has a different set of competitors and those competitors set the price," Mr Kloppers told The Australian.
And Xstrata chief executive Mick Davis said from South Africa: "The government needs to do what it should have done all along and enter into full and open consultations with the industry where every aspect of the super tax is open for debate. Tinkering at the margins will not avoid the significant long-term damage this tax could do to mining investment in Australia.
"The government should stop negotiating with itself and start consulting with the industry."
Rio Tinto chairman Jan du Plessis told the company's shareholders that Australia's reputation had already been damaged by the super-profits tax proposal.
"We are concerned that the proposed resources super tax will erode Australia's competitiveness, severely curtail investment and limit jobs growth," Mr du Plessis said yesterday. He said that some of the government's arguments for the tax and some of the statistics that had been produced to support them "could only be described as scandalous, totally scandalous".
Wayne Swan continued his criticisms of the mining companies yesterday, telling parliament they were still paying only 17c in the dollar in tax compared with the "headline rate" of 30 per cent. The Treasurer vowed to keep the 40 per cent rate for the new RSPT.
"What we have to do is extract the maximum value for the Australian people as we go forward to reform our economy, to invest in our economy and to ensure our prosperity as we go forward," Mr Swan said.
Earlier, he said the government was "interested and fair dinkum about consultation".
"The government is involved in consultation," Mr Swan said. "First of all, we have our consultation panel. Over 80 companies have been through that panel process and are talking to that panel. In addition to that, the government is continuing to talk to many mining companies about their views.
"What we are going to get for the Australian people is a fair share of the resources they own 100 per cent, a fair share - a tax which encourages investment and growth in the industry."
The government's consultation panel, headed by Treasury deputy secretary David Parker, will give its first report to the government tomorrow. It is expected to go beyond its strict limits for discussion and recommend the raising of the threshold for the super-profits tax to be lifted from 6 per cent, the long-term government bond rate, to about 11 or 12 per cent, the bond rate plus five or six percentage points.
As reported in The Australian on Monday, the lost revenue would be covered by the withdrawal of the 40 per cent compensation for failed projects to enable the government to keep its budget projections, including a $1bn surplus in 2012-13, intact.
Mr Parker said yesterday the proposed RSPT as a result of the Henry tax review was "the architecture of reform, not the engineering drawings".
"With such reforms, there will always be winners and losers, with some groups more vocal than others," Mr Parker said. "The challenge is to work together to address the issues that will inevitably arise."
Government sources confirmed that the panel was expected to recommend major changes to the proposed RSPT, including raising the threshold, but others warned it was unlikely there would be an early settlement of the negotiations with the mining companies.
In Adelaide, Mr Kloppers said a 40 per cent tax rate may have been considered appropriate when it was devised for the petroleum industry in the 1980s after two years of consultation but it was "a giant, naive extrapolation to think miraculously the same one is the appropriate rate for every mineral in 2010".
"BHP Billiton, being in the oil and gas industry and in the minerals industry, has experience on both sides and, more than other players, we understand the difference between the products themselves and between minerals more broadly," he said.
"Retrospectivity on this tax is the key determinant for Australia as a destination for investment.
"It goes against the core offering that Australia has, which is being a stable place for investment."
67 comments on this story
Remember we are not financial advisors.. Sampson management Services (SMS) educate and inform only...We are Asset Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach. Ref standards:AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
Tuesday, May 25, 2010
tips
yesterday AUZ Australian mines had a good PSA - Price sensitive announcement and it went up 25%.. you can see the volume risers on the www.asx.com.au price/market stats.
Remember we are not financial advisors.. Sampson management Services (SMS) educate and inform only...We are Asset Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach. Ref standards:AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
Remember we are not financial advisors.. Sampson management Services (SMS) educate and inform only...We are Asset Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach. Ref standards:AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
Monday, May 24, 2010
May 21 2010 all global indices fell- and FNT
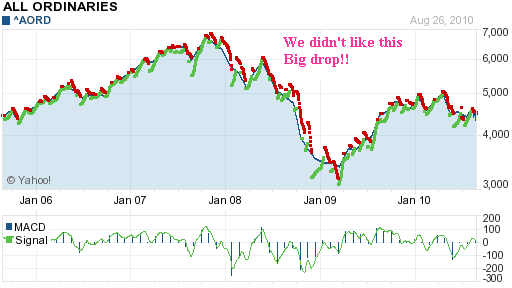
If you watch the financial news you'll hear that on Monday 24 May 2010, everything was rising again and tv newsreaders will say that the market rose by ..4% for example.BUT IT ROSE from its worst low since july 2009!
at 4330 it's still nowhere near its most recent high ..over 7000 points in Nov 2007.Its like facing a set of stairs. there is still a long way to the top and it might take 18 months to 2 years IF there are no more taxes, wars, drought, political unrest, volcanoes, major disease etc...
There will always be some companies rising when others fail but you need to do a lot of research, and then have some luck.
you could help yourself by watching the Price sensitive announcements (PSA)on the home page of the asx. www.asx.com.au and then chart them to see if you think they might attract predator buyers who will push the price up.. and remember this quote,
The Best of Times -- the Worst of Times
In 1859, Charles Dickens wrote in 'A Tale of Two Cities':
"It was the best of times, it was the worst of times; it was the age of wisdom; it was the age of foolishness; it was the epoch of belief, it was the epoch of incredulity; it was the season of Light, it was the season of Darkness; it was the spring of hope, it was the winter of despair ..."
be cautious, be careful and judge wisely.
FNT Frontier resources is a gold miner in New Guinea, therefore not concerned about the Aussie Govt's proposed 40% resource tax. They claim they have had some good results. Yesterday they had a Price sensitive announcement and were at .075 when I bought some. Worth buying a small parcel,under ten cents and promising..
Remember we are not financial advisors.. Sampson management Services (SMS) educate and inform only...We are Risk Asset Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach. Ref standards:AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
at 4330 it's still nowhere near its most recent high ..over 7000 points in Nov 2007.Its like facing a set of stairs. there is still a long way to the top and it might take 18 months to 2 years IF there are no more taxes, wars, drought, political unrest, volcanoes, major disease etc...
There will always be some companies rising when others fail but you need to do a lot of research, and then have some luck.
you could help yourself by watching the Price sensitive announcements (PSA)on the home page of the asx. www.asx.com.au and then chart them to see if you think they might attract predator buyers who will push the price up.. and remember this quote,
The Best of Times -- the Worst of Times
In 1859, Charles Dickens wrote in 'A Tale of Two Cities':
"It was the best of times, it was the worst of times; it was the age of wisdom; it was the age of foolishness; it was the epoch of belief, it was the epoch of incredulity; it was the season of Light, it was the season of Darkness; it was the spring of hope, it was the winter of despair ..."
be cautious, be careful and judge wisely.
FNT Frontier resources is a gold miner in New Guinea, therefore not concerned about the Aussie Govt's proposed 40% resource tax. They claim they have had some good results. Yesterday they had a Price sensitive announcement and were at .075 when I bought some. Worth buying a small parcel,under ten cents and promising..
Remember we are not financial advisors.. Sampson management Services (SMS) educate and inform only...We are Risk Asset Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach. Ref standards:AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
Tuesday, December 8, 2009
a few Xmas presents
If I was going to give you a Xmas present, I'd give you some shares in FMG (Fortesque metals about 4.20 each)
because I KNOW that CEO Twiggy (Andrew Forrest) really wants to make it a success, and he has the team mentor approach will brings out the best in others. .
He is motivated. He NEEDS to win.. and he will.
So go to your banks sharebroking and invest $500-$1000.00 in FMG.
Since I don't have much money in the Kitty- I'd buy you some MHL (Monitor at .005 cents- yes at such a low price.. )
you can get 100,000 shares for your $500.00 (usually the minimum investment.)
Monitor is risky but they have no debt. They have 2 off shore rigs off WA in the Canning basin and their announcements say that they are gurgling well. They have already risen from .002 which is a 150% improvement..
PCP is another gold miner under ten cents, (My focus is on under ten cent shares) which seems to be going well, while the gold price is high... it's share price is about 10 cents and has risen by 100% over the past few months. ABY is recovering but I don't now what's happened about their un- renewed nearby tenements...
Merry Christmas and a Prosperous 2010!
from Megan
Remember we are not financial advisors..
Sampson management Services (SMS) educate and inform only...We are Asset Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach.
Ref standards:
AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
because I KNOW that CEO Twiggy (Andrew Forrest) really wants to make it a success, and he has the team mentor approach will brings out the best in others. .
He is motivated. He NEEDS to win.. and he will.
So go to your banks sharebroking and invest $500-$1000.00 in FMG.
Since I don't have much money in the Kitty- I'd buy you some MHL (Monitor at .005 cents- yes at such a low price.. )
you can get 100,000 shares for your $500.00 (usually the minimum investment.)
Monitor is risky but they have no debt. They have 2 off shore rigs off WA in the Canning basin and their announcements say that they are gurgling well. They have already risen from .002 which is a 150% improvement..
PCP is another gold miner under ten cents, (My focus is on under ten cent shares) which seems to be going well, while the gold price is high... it's share price is about 10 cents and has risen by 100% over the past few months. ABY is recovering but I don't now what's happened about their un- renewed nearby tenements...
Merry Christmas and a Prosperous 2010!
from Megan
Remember we are not financial advisors..
Sampson management Services (SMS) educate and inform only...We are Asset Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach.
Ref standards:
AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
Wednesday, October 28, 2009
ABY and Risk - MINING LEASES NOT RENEWED
I've bragged about ABY (Aditya Copper) a few times,
and this week the RISK FACTOR has been highlighted.
After battling for 18mths with a huge global downturn and rising from 11 cents to 1.60 +, ABY has been falling and badly. Why? because "the external consultants didn't renew 8 of their mining leases..adjacent to their Niffty mine". What sort of management took their eye off the ball? The mining leases are essential to their mining business !
They say that the leases were not a main part of their business, however the market is spooked and sold.
The good thing about this situation, is that although the price may drop further - because of lost confidence- shareholders can can buy back in at a lower price.
BUT IT REMINDS US, that all business, and all human endeavour (and the sharemarket) is about RISK. You must anticipate potential risk and have a plan to deal with it. The US and Australian sharemarkets are down but some companies are rising.
LKO , PDY, JRV and TAM just to name a few good resource buys under 10 cents..
Remember we are not financial advisors..
Sampson management Services (SMS) educate and inform only...We are Assett Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach. Ref standards:
AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
and this week the RISK FACTOR has been highlighted.
After battling for 18mths with a huge global downturn and rising from 11 cents to 1.60 +, ABY has been falling and badly. Why? because "the external consultants didn't renew 8 of their mining leases..adjacent to their Niffty mine". What sort of management took their eye off the ball? The mining leases are essential to their mining business !
They say that the leases were not a main part of their business, however the market is spooked and sold.
The good thing about this situation, is that although the price may drop further - because of lost confidence- shareholders can can buy back in at a lower price.
BUT IT REMINDS US, that all business, and all human endeavour (and the sharemarket) is about RISK. You must anticipate potential risk and have a plan to deal with it. The US and Australian sharemarkets are down but some companies are rising.
LKO , PDY, JRV and TAM just to name a few good resource buys under 10 cents..
Remember we are not financial advisors..
Sampson management Services (SMS) educate and inform only...We are Assett Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach. Ref standards:
AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
Monday, October 19, 2009
tips
GDA (Gondwana gold) is rising and is now about 6 cents. I bought it at .017 cents. Many of the small resource stocks are improving, but ABY is about 1.60. Even at 1.60 it is cheap and could rise to over 4.50. (it has in the past) . goto www.asx.com.au type in ABY (or GDA etc) and have a look. Go to charts and select 5 years and you will see their charted price history.
I purchased ABY in march 09 when they were only 11 cents because this company is well managed, and has paid a dividend before.
I, like most people, regret not buying more, but the market was so volatile and at its lowest, everyone had the jitters.
I've made some modest profits lately, albeit on a very small porfolio, but "little fish are sweet" as my father used to say.
I suggest you go to http://crazyjimsmith.blospot.com and consider joining the forum.
It costs $200.00 a year, but the members post tips and information. You get access to multiple views of what's happening and if you don't go into debt, and keep your cool, you could make some profits. Then you can buy things.
Remember we are not financial advisors..
Sampson management Services (SMS) educate and inform only...We are Asset Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach.
Ref standards:
AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
I purchased ABY in march 09 when they were only 11 cents because this company is well managed, and has paid a dividend before.
I, like most people, regret not buying more, but the market was so volatile and at its lowest, everyone had the jitters.
I've made some modest profits lately, albeit on a very small porfolio, but "little fish are sweet" as my father used to say.
I suggest you go to http://crazyjimsmith.blospot.com and consider joining the forum.
It costs $200.00 a year, but the members post tips and information. You get access to multiple views of what's happening and if you don't go into debt, and keep your cool, you could make some profits. Then you can buy things.
Remember we are not financial advisors..
Sampson management Services (SMS) educate and inform only...We are Asset Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach.
Ref standards:
AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
Sunday, October 11, 2009
ABY
Aby is still powering away now at 1.55 (I bought some in march 09 when and it had dropped to 11 cents.. still have some left from that price.
Atn is another copper explorer and up today to over .078 - nearly double . Friday it was .04 cents
there are heaps of cheapies. Buy now..
Remember we are not financial advisors..
Sampson management Services (SMS) educate and inform only...We are Asset Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach.
Ref standards:
AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
Monday, August 10, 2009
should we invest or not?
The Australian market is rising and it seems that the recovery is on its way, however the American unemployment figures (or Australias) may not be as good as they seem. Therefore the result may not be as rosy as suggested.They may be counting part timers and casuals as "real jobs".
There may be more pain to come. BUT if you buy wisely now, you should make money in the longer term.
I bought ABY for 12 cents in April and now they are about 79 cents. Their price 12 months ago was 2.30.
I also purchased MCW for 17 cents and they are now around 56 cents. NWT is rising and at 7 cents should give a profit in the next 12 months. There are heaps of others. it's just a matter of being able to buy and hold, without using a margin loan. But it might be a rough and scary ride, so don't invest all your eggs in one basket and only buy minimal amounts.
and don't forget..I could be wrong. so do your own homework. make your own decisions. as the great guru,WarrenBuffet says, "eat your own cooking"
Mega
Remember we are not financial advisors..
Sampson management Services (SMS) educate and inform only...We are Assett Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach.
Ref standards:
AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
There may be more pain to come. BUT if you buy wisely now, you should make money in the longer term.
I bought ABY for 12 cents in April and now they are about 79 cents. Their price 12 months ago was 2.30.
I also purchased MCW for 17 cents and they are now around 56 cents. NWT is rising and at 7 cents should give a profit in the next 12 months. There are heaps of others. it's just a matter of being able to buy and hold, without using a margin loan. But it might be a rough and scary ride, so don't invest all your eggs in one basket and only buy minimal amounts.
and don't forget..I could be wrong. so do your own homework. make your own decisions. as the great guru,WarrenBuffet says, "eat your own cooking"
Mega
Remember we are not financial advisors..
Sampson management Services (SMS) educate and inform only...We are Assett Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach.
Ref standards:
AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
Saturday, March 14, 2009
Tip MACQUARIE COUNTRYWIDE TRUST (MCW)
todays free tip
MACQUARIE COUNTRYWIDE TRUST (MCW) is up. it was 13.5 cents on 9.3.09 and on the 15.3.09 had risen to 17.5 cents
Makes sense really.
Interest rates are down, the market seems to have bottomed, (I predicted the bottom as 19.2.09) so property is sure to rise.
if you think of the sharemarket cycle, as a circle. Then we are at the top of the circle, about to move back down the right side to a new bull market. Probably driven by property.
if you can't afford real property, then buy some property shares.
This is cheap.
The recovery could happen quickly, or may take a few months.
I think by next Xmas, we'll see a good sharemarket rise.
Mega
Disclaimer: I/we do not own any of these.. yet
Remember we are not financial advisors..
Sampson management Services (SMS) educate and inform only...We are Assett Management Consultants-
we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach.
Ref standards: AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
MACQUARIE COUNTRYWIDE TRUST (MCW) is up. it was 13.5 cents on 9.3.09 and on the 15.3.09 had risen to 17.5 cents
Makes sense really.
Interest rates are down, the market seems to have bottomed, (I predicted the bottom as 19.2.09) so property is sure to rise.
if you think of the sharemarket cycle, as a circle. Then we are at the top of the circle, about to move back down the right side to a new bull market. Probably driven by property.
if you can't afford real property, then buy some property shares.
This is cheap.
The recovery could happen quickly, or may take a few months.
I think by next Xmas, we'll see a good sharemarket rise.
Mega
Disclaimer: I/we do not own any of these.. yet
Remember we are not financial advisors..
Sampson management Services (SMS) educate and inform only...We are Assett Management Consultants-
we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach.
Ref standards: AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
Wednesday, February 18, 2009
The tide has turned.. the bear is not growling!
Mega at Megamoneybox thinks the tide has turned and the recovery is on the way.
other writers say that when the recovery starts, the highest growth will be in the first 100 days, so start doing your homework.. NOW
check back to see if she was right today 19.02.2009.
Remember we are not financial advisors..
Sampson management Services (SMS) educate and inform only...We are Assett Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach.
Ref standards:
AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
other writers say that when the recovery starts, the highest growth will be in the first 100 days, so start doing your homework.. NOW
check back to see if she was right today 19.02.2009.
Remember we are not financial advisors..
Sampson management Services (SMS) educate and inform only...We are Assett Management Consultants- we teach you about risk and how to measure that risk according to the international standards on Quality, Environment, OHS, and Risk management in an integrated approach.
Ref standards:
AS/NZS/ISO 9001, AS/NZS/ISO 14001, AS/NZS/ISO 4804, AS/NZS/ISO 4360.
Subscribe to:
Posts (Atom)